SIP vs Lump Sum Investment: Which Is Right for You?
Quick Answer
Neither SIP nor lump sum is universally “better”, it depends on your cash flow and market timing risk.
SIPs work best when you are investing from regular income and want to average out market volatility. Lump sum works best when you have a large amount ready to deploy and markets aren’t at a clear high. Most long-term investors are better served by SIPs simply because they remove the need to time the market.
Why this question keeps coming up
Every few months, someone gets a bonus, an inheritance, or simply saves up a large amount, and the question is the same: put it all in now, or spread it out? The honest answer isn’t exciting, but it’s the one that actually protects your money: it depends on what the money is for and how it arrived.
How SIP actually works
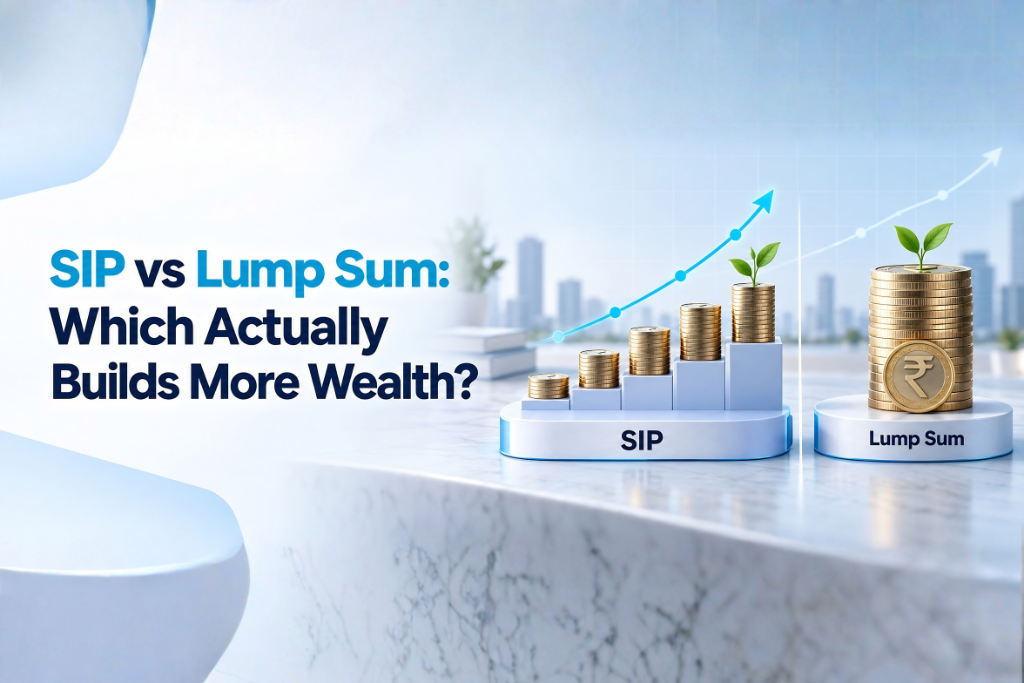
A Systematic Investment Plan means you invest a fixed amount at fixed intervals, usually monthly, regardless of whether the market is up or down. The mechanism that makes this useful is rupee cost averaging: when prices are high, your fixed amount buys fewer units; when prices fall, it buys more. Over time, this averages out your purchase cost instead of betting everything on one entry point.
This isn’t a return-boosting trick, it’s a risk-management tool. It removes the need to guess when markets will rise or fall, which is precisely the guess even professional investors get wrong regularly.
How lump sum works, and when it wins
A lump sum investment puts the full amount to work on day one. If markets rise steadily afterward, a lump sum invested early outperforms a SIP of the same total amount, because more money was exposed to growth for longer. Lump sum tends to make sense when:
- The money became available all at once (bonus, sale of an asset, inheritance) and there’s no reason to artificially delay it.
- You have a long investment horizon (7+ years), reducing the impact of short-term volatility.
- Markets aren’t visibly overheated relative to their own recent history.
The comparison, side by side
Factor | SIP | Lump Sum |
Best suited for | Regular income (salary, business cash flow) | One-time large amounts |
Market timing risk | Low, spreads entry points | Higher, single entry point |
Discipline required | Built-in (automated) | Requires a separate plan |
Ideal horizon | Any, but shines over 5+ years | Best with 7+ year horizon |
Common mistake | Stopping SIPs when markets fall | Deploying everything at a market peak out of urgency |
What we tell clients
The honest position, and the one that matches 29 years of watching both approaches play out is that most people aren’t actually choosing between SIP and lump sum in isolation. They have some regular income and occasional lump sums. The realistic approach is usually both: a running SIP for discipline, and a separate, considered plan (sometimes a staggered deployment over a few months, not lump sum on day one) for windfalls.
What we actively advise against: deploying a large lump sum in a single day purely out of impatience, or stopping a SIP the moment markets correct that second one is the single most common wealth-destroying decision we see in otherwise well-planned portfolios.
Can I do both SIP and lump sum in the same fund?
Yes. Many investors run a monthly SIP for discipline and add lump sum top-ups (often staggered rather than all at once) when they have surplus cash.
Is SIP better than a lump sum for beginners?
For most first-time investors, yes, SIPs remove the pressure of picking a "right" entry point and build a saving habit alongside an investing one.
Does SIP guarantee better returns than lump sum?
No, neither method guarantees returns, and which performs better in hindsight depends entirely on the market path taken. SIP reduces timing risk; it doesn't eliminate market risk.
What happens if I stop my SIP when the market falls?
You lock in the fall as a loss and miss the lower-priced units that a continuing SIP would have bought, historically one of the costliest mistakes investors make
Disclaimer: Mutual fund investments are subject to market risks. Past patterns of market behavior are not indicative of future returns. This article is for educational purposes and does not constitute investment advice specific to any individual.
Leave a Reply